CEB Contributor
Heidi Imsand Slater
Content Attorney at Continuing Education of the Bar (CEB)
Heidi Imsand Slater has nearly a decade of experience in estate planning and administration. She most recently worked at Fennemore Wendel in Oakland and prior to that worked at a boutique trust and estate firm in Danville, CA. Ms. Slater attended law school at the University of California Law, San Francisco (formerly UC Hastings) and thereafter obtained her LL.M. in Taxation from the University of San Francisco. She has been certified by the California State Bar as a Specialist in Estate Planning, Trust & Probate Law and has been rated a Super Lawyers Rising Star every year since 2018, until joining CEB.
CEB Region:
Bay Area Region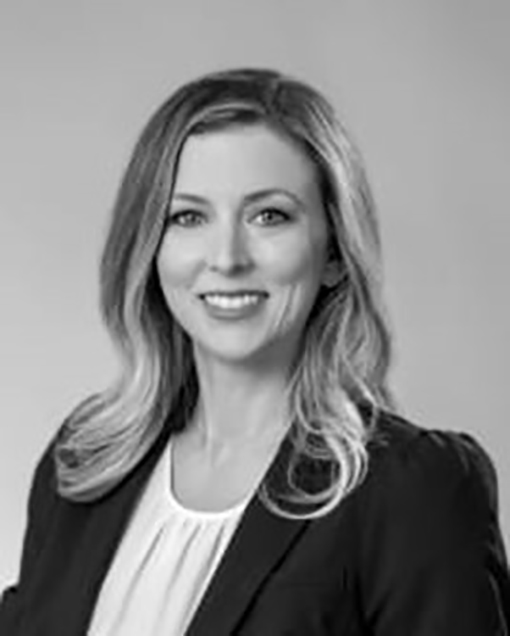
Content by Heidi Imsand Slater
-
Supreme Court Hears Challenge to Termination of TPS Status for Syria and Haiti
May 26, 2026
Heidi Imsand Slater
Administrative Law, Constitutional Law, Immigration Law
On April 29, the last day of oral arguments for its October Term 2025, the U.S. Supreme Court
'Real Housewife' Gizelle Bryant Gets Real About Testamentary Capacity
May 5, 2026
Heidi Imsand Slater
Trusts & Estates, Estate Planning, Trust & Probate Litigation
A person can learn a lot from watching Bravo's “Real Housewives” series. A non-exhaustive list:
At Oral Argument, Majority of Supreme Court Justices Seem Skeptical of Trump’s Position on Birthright Citizenship
April 13, 2026
Heidi Imsand Slater
Constitutional Law, Immigration Law
On his Inauguration Day, President Donald Trump signed the

First District Addresses When a Claim for Intentional Interference With Inheritance May Be Brought in California
March 24, 2026
Heidi Imsand Slater
Appellate Law, Trusts & Estates, Trust & Probate Litigation
When a would-be beneficiary finds themselves left out of an estate plan—or at least taking a smaller slice of the pie than they were expecting—they might wonder what, if any, recourse they have against those “responsible” for their predicament. A recent case out of California's First District Court of Appeal,
In 6-3 Ruling, U.S. Supreme Court Strikes Down the Trump Tariffs
March 3, 2026
Heidi Imsand Slater
Constitutional Law, Tax Law
On Feb. 20, the U.S. Supreme Court issued its much anticipated
At Oral Arguments, Supreme Court Seems Poised to Keep Fed Governor in Place Pending Litigation
February 10, 2026
Heidi Imsand Slater
Appellate Law, Constitutional Law
On Jan. 21, the U.S. Supreme Court

California's First District Addresses Insufficient Pleading of Dependent Adult Abuse Claim in Childbirth Case
January 20, 2026
Heidi Imsand Slater
Appellate Law, Personal Injury, Trusts & Estates, Elder Law
The dispute in
IRS and U.S. Treasury Issue Guidance on Operation of 'Trump Accounts'
December 29, 2025
Heidi Imsand Slater
Tax Law, Trusts & Estates, Estate Planning
The federal One Big Beautiful Bill Act (Pub.L. No. 119–21 (July 4, 2025) 139 Stat. 72), enacted earlier this year, introduced a new savings vehicle called “Trump accounts.” (See Int.Rev. Code, § 530A.) Beginning in 2026, parents, family members and other donors can contribute a specified amount each year into a Trump account for the benefit of a minor.
After Oral Arguments, Supreme Court Seems Likely to Rule Against Trump's Tariffs
November 18, 2025
Heidi Imsand Slater
Constitutional Law, Tax Law
In September, CEB covered the Federal Circuit Court’s decision holding that many of President Donald Trump’s tariffs
When Taking Responsibility for a Minor Child, 'Witch' Option Is Best?
October 28, 2025
Heidi Imsand Slater
Trusts & Estates, Estate Planning, Guardianships & Conservatorships
One of my earliest memories is of a trip to the bank with my mom. While waiting in line for the teller, I turned to my mom, terrified, because in front of us was a woman who I was certain was the Grand High Witch from the 1990 movie "The Witches." In reality, that just meant this woman looked like Anjelica Huston (a compliment, really!), but Early-90s Me did not grasp the distinction.
Not Just a Bunch of Hocus Pocus: How the Sanderson Sisters Could Have Benefited from Estate Planning
October 6, 2025
Heidi Imsand Slater
Trusts & Estates, Estate Planning, Probate Administration, Trust Administration
Since the 1993 release of the cinematic tour de force "Hocus Pocus," I’ve watched the film every year to usher in the Halloween season. "Hocus Pocus"
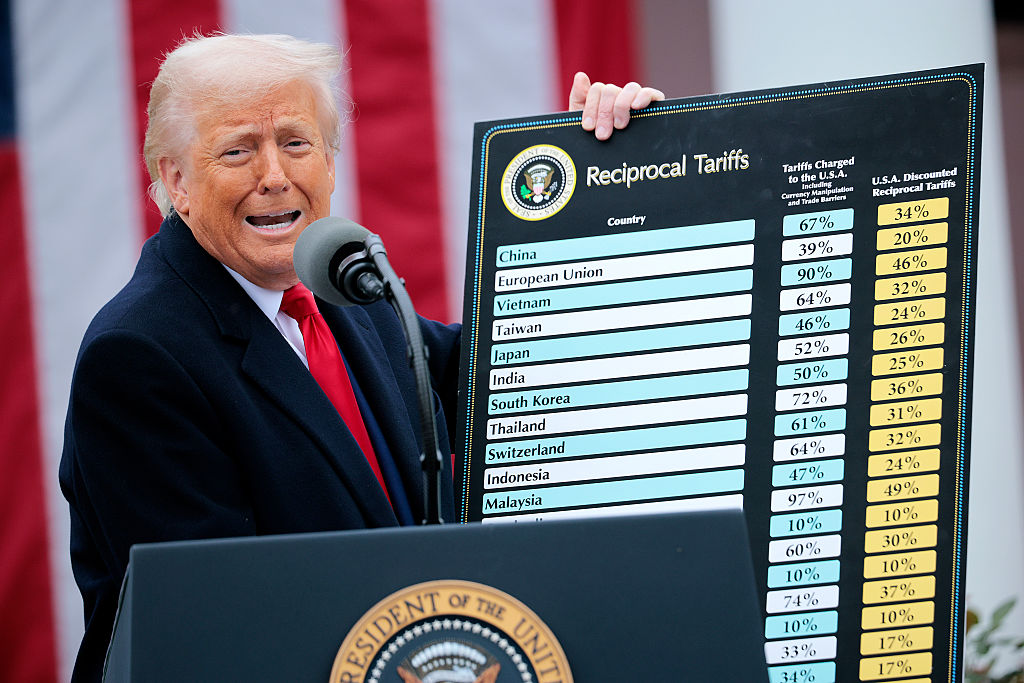
SCOTUS Will Review Federal Circuit Court Decision Finding Trump's Tariffs Unlawful
September 15, 2025
Heidi Imsand Slater
Constitutional Law, Tax Law
Last month, the Court of Appeals for the Federal Circuit entered its
DOGE Tries to Dodge Federal Lawsuit Challenging Its Access to Taxpayer Data
August 26, 2025
Heidi Imsand Slater
Administrative Law, Privacy & Information Security, Tax Law
Of the many lawsuits that have been brought to contest the actions of the Trump administration, one is focused on the legality of the Department of Government Efficiency’s (DOGE) access to taxpayer data and its intent to share this data across federal agencies. The ongoing case comes with major implications for taxpayers' privacy and the reach of the federal executive branch.
Second District Confirms Limits on Who May Petition for a Conservatorship
August 5, 2025
Heidi Imsand Slater
Trusts & Estates, Guardianships & Conservatorships, Trust & Probate Litigation
Often, a key difficulty in protecting a vulnerable adult is finding someone willing to take on the weighty responsibility of a conservatorship or other protective proceeding. In a recent case out of California's Second District Court of Appeal,

What Do Squid Game and Probate Court Have in Common? In Both, Surprise Babies Can Be Quite the Plot Twist
July 15, 2025
Heidi Imsand Slater
Trusts & Estates, Probate Administration, Trust Administration, Trust & Probate Litigation
As soon as season three of Netflix’s
In Estate of Spizzirri, the Eleventh Circuit Confirms Limits on Deductibility of Intrafamily Payments from Estate Tax
June 24, 2025
Heidi Imsand Slater
Tax Law, Trusts & Estates, Trust Administration
When determining the size of a decedent’s taxable estate, a key consideration is the extent to which the estate is entitled to deduct items from the estate’s value. Any deduction will, in turn, reduce the potential estate tax liability. Available deductions include those for funeral expenses, expenses of administration, charitable transfers, and transfers to a spouse. (See Int.Rev. Code, §§ 2053–2058.)
The State of Small Estate Procedures in California After AB 2016: Everything You Need to Know
June 10, 2025
Heidi Imsand Slater
Trusts & Estates, Probate Administration, Trust Administration
In September 2024,
Only YOU Can Prevent Tax Scams: The IRS Releases Its 'Dirty Dozen' for 2025
May 13, 2025
Heidi Imsand Slater
Tax Law
Much like the warnings I give my mom about not sharing her personal information with the “USPS worker” who just texted her or the “Apple Support technician” who called about her non-Apple computer, every year the IRS releases an annual “
Partition and Recreation: Amundson v. Catello as Explained by Pawnee’s Finest
April 22, 2025
Heidi Imsand Slater
Real Property, Trusts & Estates, Probate Administration
In the recent case
In People v. Jones, Withdrawal of Life Support Could Not 'Fracture' a Murder Conviction
April 1, 2025
Heidi Imsand Slater
Criminal Law, Trusts & Estates, Estate Planning
Of all the memorable things the spring of 2007 brought us (Britney Spears shaving her head, Barack Obama announcing his candidacy for president), not least among them was the release of the cinematic masterpiece
A Primer on Social Security Survivor Benefits
March 10, 2025
Heidi Imsand Slater
Trusts & Estates, Estate Planning
When the Department of Government Efficiency turned its sights on the Social Security Administration (SSA), reports surfaced alleging that
Child Tax Credit, Charitable Deductions, and Social Security: Recent Tax Proposals from the 119th Congress
February 18, 2025
Heidi Imsand Slater
Tax Law
The first few weeks of the Trump administration have been a legal whirlwind, to say the absolute least. With the onslaught of legal and political developments to keep track of, it can be easy to forget that some ordinary, comparatively mundane lawmaking is still taking place in the chambers of Congress. Over the last several weeks, federal lawmakers have proposed a number of bills that would impact our tax system and its administration. While only time will tell whether any of this proposed legislation will become law, below are some of these recent tax proposals:
Busting Common Estate Planning Myths
January 31, 2025
Heidi Imsand Slater
Trusts & Estates, Estate Planning, Trust & Probate Litigation
Over the course of 17 seasons, the popular Discovery Channel show
In Young v. Hartford, Fourth District Confirms That Order Suspending a Trustee’s Powers Is Not Appealable
January 6, 2025
Heidi Imsand Slater
Trusts & Estates, Trust & Probate Litigation
California's Probate Code enumerates which probate court orders can be appealed. (Prob. Code, § 1300.) Such orders include those granting or denying compensation for a fiduciary, authorization of a fiduciary’s acts, or removal of a fiduciary. (Prob. Code, § 1300(c), (e), (g).) In addition, in the case of a trust, certain additional final orders are appealable -- including final orders under Probate Code sections 17200–17211, 19020–19030, and 20100–20225. (Prob. Code, § 1304.)
In re the Guardianship of Buddy the Elf: An Outtake (I Assume) from the Holiday Classic
December 17, 2024
Heidi Imsand Slater
Trusts & Estates, Guardianships & Conservatorships
Holiday movies often try to teach their viewers important life lessons and values: the importance of giving, of family, and of treating others with kindness. One modern classic,

In Hamlin v. Jendayi, First District Confirms Intestate Heirs Have Standing to Contest a Trust
November 25, 2024
Heidi Imsand Slater
Trusts & Estates, Trust & Probate Litigation
Several years ago, the California Supreme Court addressed whether beneficiaries of an earlier trust iteration had standing to contest later amendments to that trust that disinherited them. (See
Estate Planning Baby Steps for the Procrastinators in Our Lives
November 6, 2024
Heidi Imsand Slater
Trusts & Estates, Estate Planning
My mom recently had lunch with a family friend, whom we’ll call “Carol.” They discussed many topics (including, I assume, my mom’s favorite/only daughter), but eventually the conversation turned to Carol’s home and family situation. Whether because of my estate planning background or because of my mom’s Type-A hyper-organized personality, she shared with me her shock at what Carol relayed. The highlights of Carol’s story, according to my mom:
Liars and Scammers and Frauds, Oh My! The IRS Warns of Top Tax Schemes for 2024
October 14, 2024
Heidi Imsand Slater
Tax Law
It’s Halloween time, which means children, teens, and cool adults will dress up as monsters, ghouls, and other spooky creatures. But if any of these revelers happened to read the Internal Revenue Service’s “
In Grossman v. Wakeman, Second District Addresses Attorneys’ Limited Duties to Third Parties
September 23, 2024
Heidi Imsand Slater
Trusts & Estates, Estate Planning, Trust & Probate Litigation
While estate planning can be an especially congenial and rewarding practice area, it also presents unique stresses. Perhaps chief among these stresses is the fact that not only do the estate planner’s actions impact their client, but also their client’s families, beneficiaries, and omitted heirs. Thus, not only might the planner be confronted with complaints from an unhappy client, but also from confused or disgruntled beneficiaries (or would-be beneficiaries).

It’s the Circle of Life (and Death): How Probate Rules Would Have Saved Pride Rock
September 3, 2024
Heidi Imsand Slater
Trusts & Estates, Estate Planning, Probate Administration
There are many things I enjoy about spending time with my 4-year-old nephew. For example, I get to hear his cute little laugh when he thinks something is funny, and he gives me many more legitimate opportunities to have ice cream (can’t let the kid eat alone!). But one of the best things is watching my favorite childhood movies with him and getting to experience them again through his eyes.
Not Even on Death Will We Part: Conditioning Gifts on Marriage in California
August 13, 2024
Heidi Imsand Slater
Trusts & Estates, Estate Planning, Trust & Probate Litigation
In my
Capacity, Communication, and the Count of Monte Cristo
July 23, 2024
Heidi Imsand Slater
Trusts & Estates, Estate Planning, Elder Law, Trust & Probate Litigation, Contests of Wills, Trusts & Other Donative Instruments
A bedrock principle of estate planning is that for a testator’s will to be valid, the testator must have had sufficient mental capacity to sign the will. Unfortunately, evaluating a client’s capacity can be especially difficult when they are of advanced age or suffer from a mental or physical disorder.
Moore Money, Moore Problems: Supreme Court Holds U.S. Shareholders Can Be Taxed on Foreign Entity Income
July 1, 2024
Heidi Imsand Slater
Tax Law, Trusts & Estates
On June 20, the U.S. Supreme Court issued its highly anticipated (at least in the tax world)
Newman v. Casey Explores Limits on Relief That Can Be Granted as Part of Elder Abuse Restraining Orders in California
June 11, 2024
Heidi Imsand Slater
Trusts & Estates, Elder Law, Trust & Probate Litigation
A recent case out of the First District Court of Appeal,
Robinson v. Gutierrez Clarifies Meaning of 'Remuneration' as Applied to Caregivers for Dependent Adults in California
May 21, 2024
Heidi Imsand Slater
Trusts & Estates, Trust & Probate Litigation
A recent California
Not So Fast (and the Furious): Probating a Missing Person’s Estate
April 26, 2024
Heidi Imsand Slater
Trusts & Estates, Probate Administration
The "Fast and the Furious" franchise has many recurrent themes: the importance of family, the superiority of Corona, and the sheer implausibility of most plot points. (Note: spoilers ahead.) I’ve watched Vin Diesel
Highlights from the Biden Administration’s Greenbook for Fiscal Year 2025
April 9, 2024
Heidi Imsand Slater
Tax Law, Trusts & Estates, Estate Planning, Advanced Tax Planning
On March 11, 2024, the U.S. Treasury Department released its
Not That Innocent: Thomas v. Commissioner Explores Limits on Innocent Spouse Tax Relief Claims
March 19, 2024
Heidi Imsand Slater
Family Law, Tax Law
Spouses who file joint tax returns are jointly and severally liable for the taxes owed on their aggregate income. (Int.Rev. Code, § 6013(d)(3).) In other words, even if Spouse 1 earned all the income reported on the return, Spouse 2 is still on the hook for the resulting tax liability. The tax code recognizes, however, that this can sometimes work an injustice. One avenue for addressing such potential inequity is “innocent spouse” relief under Internal Revenue Code section 6015.
In Sickness, Health, and Substituted Judgment: Jay Leno Seeks Probate Court Relief in Light of Wife’s Diminishing Capacity
February 27, 2024
Heidi Imsand Slater
Trusts & Estates, Estate Planning, Guardianships & Conservatorships
Last month, comedian Jay Leno filed a petition in Los Angeles County to establish a conservatorship over his wife, Mavis Leno. After years of progressive decline in Mavis’s capacity, Leno’s petition seeks permission from the court to establish an estate plan on Mavis’s behalf. According to Leno’s petition, the estate plan would ensure Mavis is adequately cared for in the event of Leno’s death and would provide for the ultimate disposition of their assets.
Who Owns Trust Property? Trust Law Principles Hit the Congressional Stage
February 6, 2024
Heidi Imsand Slater
Trusts & Estates, Estate Planning
Last month, a pair of congressional debates were held regarding whether to hold a particular witness in contempt of Congress for defying a congressional subpoena. Those watching the debates likely expected the heated back-and-forth that took place about the validity of the subpoena and the appropriate remedy for failing to fully comply with it. Few, I imagine, expected a debate to arise about foundational trust law principles.
The Reality of How Separation Can Affect Estate Planning
January 16, 2024
Heidi Imsand Slater
Family Law, Trusts & Estates, Estate Planning
For those not immediately familiar with the name Kyle Richards, she has several claims to fame: Kyle played the little neighborhood girl in "Halloween"
‘Twas the Night Before Reassessment: How the Family Farm Exclusion Worked a Holiday Miracle
December 22, 2023
Heidi Imsand Slater
Trusts & Estates, Estate Planning
It’s a tale as old as time (or at least as old as the Hallmark network):
The Golden Bachelor May Face Omit-ment Issues
December 5, 2023
Heidi Imsand Slater
Trusts & Estates, Estate Planning, Trust & Probate Litigation
For any fan of reality television—or of love—ABC’s
The California Slayer Statutes (Taylor's Version)
November 14, 2023
Heidi Imsand Slater
Trusts & Estates, Estate Planning, Probate Administration, Trust & Probate Litigation
Despite being the greatest singer-songwriter in a generation (according to some) (me), Taylor Swift has had plenty to worry about. A non-exhaustive list: whether another acceptance speech of hers will get interrupted, whether the bridge of her next song will be as amazing as the last one (it will be), and whether Travis Kelce’s mom really said that meeting Taylor was only “okay.”
Taxation of Real Property: It Even Scares the Ghosts
October 24, 2023
Heidi Imsand Slater
Tax Law, Trusts & Estates, Estate Planning
If you’ve ridden the Disneyland attraction The Haunted Mansion, you know it's home to a troupe of ghosts who don’t (or can’t?) seem to leave. To get to the bottom of what these ghosts are up to and why, CEB dispatched an investigative journalist to travel to the Haunted Mansion and study the ghosts who reside there. No one could have predicted what we would uncover.
Harry Potter and the Secret Incapacity Plan
October 3, 2023
Heidi Imsand Slater
Trusts & Estates, Estate Planning
CEB recently investigated the ruins believed to be the California vacation residence of the late Lord Voldemort. As part of that investigation, CEB uncovered lost journal entries that appear to have been intended for a memoir chronicling Voldemort’s achievements (his words, not ours). Below are selected excerpts from these writings. Where appropriate, CEB has added notations in italics. Reader discretion is advised.
How Proactive Estate Planning Can Help Avoid a Conservatorship 'Blindside'
September 12, 2023
Heidi Imsand Slater
Trusts & Estates, Estate Planning, Guardianships & Conservatorships
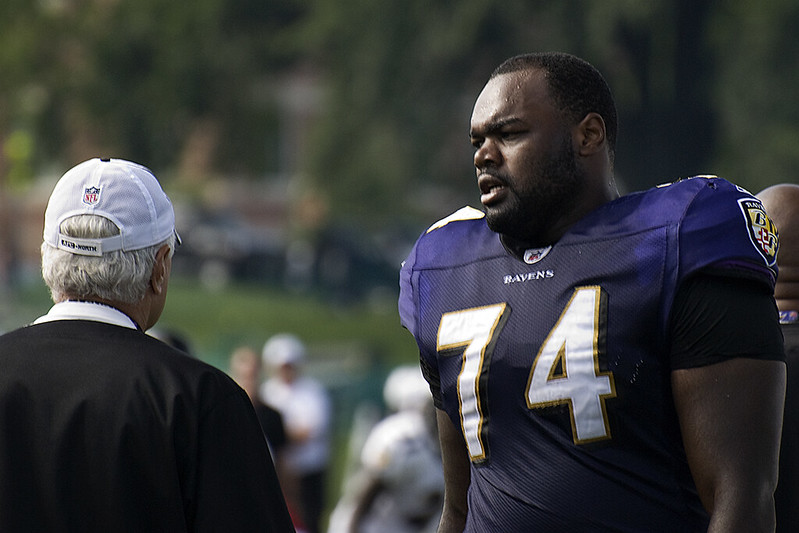
For those who have seen the 2009 movie "The Blind Side", the story of football player Michael Oher is familiar. According to the film, teenaged Oher was without a home or a supportive family, until his life was turned around when a well-to-do family, the Tuohys, took him into their home and adopted Oher as their own. The Tuohys helped Oher fully realize his football talents, and he was eventually drafted by the Baltimore Ravens as a first-round draft pick. It was a heartwarming story, praised by audiences and critics alike.
Keeping the Power in Powers of Attorney
August 22, 2023
Heidi Imsand Slater
Trusts & Estates, Estate Planning, Probate Administration, Trust Administration
Earlier this month, reports circulated that U.S. Senator Dianne Feinstein (D-Cal.) ceded authority over at least some of her affairs to her daughter Katherine Feinstein. This came to light when Katherine
R-E-S-P-E-C-T the Requirements for Holographic Wills
August 1, 2023
Heidi Imsand Slater
Trusts & Estates, Estate Planning, Trust Administration, Trust & Probate Litigation
While singular in many respects, the Queen of Soul is relatable in at least one way: after her death, her estate became embroiled in litigation over conflicting testamentary documents.
'Scandoval' and the Risks of Co-owning Real Property
July 13, 2023
Heidi Imsand Slater
Real Property, Trusts & Estates, Estate Planning, Trust Administration
It is frequently said that our nation is more divided now than it has been at any other time in recent history. Enter, “Scandoval” to unite us.
-
Exploring Strategies to Minimize Property Tax Reassessment Upon Transfer (Real Property Tax Reassessment)
Trusts & Estates, Estate Planning, Real Property Tax Reassessment
Explore various techniques for avoiding property tax reassessment on the transfer of real property. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Prepare an Informal Accounting
Trusts & Estates, Trust Administration, Trustee's Status Reports and Accounting
This how-to guide addresses how to prepare an informal accounting for a trust under Probate Code section 16063. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Letter to Trustee Explaining Accounting Options
Trusts & Estates, Trust Administration, Trustee's Status Reports and Accounting
Use this letter to explain to the trustee the relative pros and cons of providing the beneficiaries with a formal accounting, an informal accounting, or seeking waivers from the trust beneficiaries of their right to an accounting. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Informal Accounting
Trusts & Estates, Trust Administration, Trustee's Status Reports and Accounting
This sample informal accounting is designed to satisfy the requirements of Probate Code section 16063. An informal accounting should be accompanied by a section 16063-compliant cover letter (see the Sample Cover Letter with Informal Accounting in the Related Documents section below).
-
Sample Letter to Trustee on Annual Accounting Obligations
Trusts & Estates, Trust Administration, Initial Post-Death Administration
Provide this sample letter to the trustee to explain their duty to account to the beneficiaries, including the preparation of accounts and the risks of failing to satisfy this duty. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Ensuring the Trustee Complies with Annual Accounting Obligations
Trusts & Estates, Trust Administration, Initial Post-Death Administration
Obtain strategic tips and guidance on how to ensure the trustee satisfies their duty to account to the beneficiaries. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Deciding How to Satisfy the Trustee’s Accounting Obligations
Trusts & Estates, Trust Administration, Initial Post-Death Administration
This chart addresses the relative pros and cons of the methods available to satisfy the trustee’s duty to account to trust beneficiaries under Probate Code section 16062, subdivision (a). We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Inventory of Decedent's Assets
Trusts & Estates, Trust Administration, Initial Post-Death Administration
Use this sample spreadsheet to make an initial inventory of the decedent’s assets at the start of the administration. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Beneficiary Acknowledgment of Receipt of Preliminary Distribution (Trust Administration)
Trusts & Estates, Trust Administration, Initial Post-Death Administration
Use this sample form to obtain a beneficiary’s acknowledgment of receipt of a trust distribution. This document should be enclosed with a cover letter to the beneficiary, the distribution check, or any other pertinent enclosures.
-
Sample Essential Information Cover Sheet (Trust Administration)
Trusts & Estates, Trust Administration, Initial Post-Death Administration
Use this sample trust administration cover sheet to conveniently access basic information about the administration. Having quick and easy access to this information can help save time and frustration when, for example, fielding beneficiary phone calls or completing administration paperwork.
-
Topics to Discuss with Trustee-Client at Initial Meeting (Trust Administration)
Trusts & Estates, Trust Administration, Initial Post-Death Administration
Use this checklist to help guide you through your initial meeting with a new trust administration client, ensuring you address the most critical items with the client at the outset. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Trustee Timekeeping Ledger (Trust Administration)
Trusts & Estates, Trust Administration, Initial Post-Death Administration
Provide the trustee with this sample timekeeping ledger to help them contemporaneously track the time they spend on the trust administration. This ledger is intended to support the trustee’s claim to compensation and help fend off any potential challenges.
-
Sample Client Instruction Letter for Revocation of Power of Attorney
Trusts & Estates, Estate Planning
Send this letter of instruction to your client along with the prepared revocation of their power of attorney for financial management. The letter informs your client of how to execute and disseminate the revocation appropriately.
-
Sample Attorney Drafted Form of Power of Attorney for Financial Management
Trusts & Estates, Estate Planning, Powers of Attorney for Financial Management
Use this attorney-drafted power of attorney for financial management as a component of a complete estate plan to allow a client to designate a financial decision maker to assist with management of their financial affairs. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Form of Revocation of Power of Attorney for Financial Management
Trusts & Estates, Estate Planning, Powers of Attorney for Financial Management
Use this sample form to revoke a durable power of attorney, whether the power of attorney is attorney-drafted or a California statutory form. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Chart: Is a Clayton QTIP Appropriate?
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Use this chart to assess the relative advantages and disadvantages of using Clayton QTIP trust provisions compared to other trust funding structures. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Clayton QTIP Provisions
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Use this sample language when drafting an A/B/C trust that will utilize Clayton QTIP funding provisions at the first spouse’s death. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample QDOT Provisions
Trusts & Estates, Estate Planning, Estate Planning for Married Couples, Qualified Domestic Trusts
When drafting revocable trust for married clients with one spouse who is not a U.S. citizen, use these sample provisions to qualify the marital trust as a qualified domestic trust (QDOT) at the death of the first spouse. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Chart: Small Estate Procedure Rules Before and After AB 2016
Trusts & Estates, Probate Administration, Small Estate Transfer by Affidavit, Small Estate Transfer by Court Order
Use this chart to understand the rules applicable to small estate procedures before and after the passage of AB 2016 (eff. Jan. 1, 2025), including the value thresholds applicable to the different procedures depending on when the decedent died. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Checklist: QDOT Requirements for Noncitizen Spouses
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
If preparing an A/B/C trust for a married couple with one noncitizen spouse, use this checklist to ensure the QTIP trust meets the requirements of a qualified domestic trust (QDOT) under Internal Revenue Code section 2056A. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Determining the Appropriate Funding Formula (A/B/C Trusts)
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Understand the comparative advantages of selecting either a pecuniary formula or a fractional share formula when drafting the subtrust funding provisions for an A/B/C trust. For those less familiar with pecuniary formulas and funding options, review the articles in the “Related Documents” section before proceeding.
-
Sample Transmittal Letter to Client with Draft A/B/C Trust
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Use this letter to ensure your clients are adequately informed of the critical elements of their draft estate planning documents, including their A/B/C trust, wills, powers of attorney for health care and financial affairs, and other ancillary documents. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Pecuniary Formula Clauses
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
When drafting an A/B/C trust, use these sample formula clauses to divide the deceased spouse’s assets between the bypass trust and the QTIP trust using a pecuniary marital deduction amount. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Fractional Share Formula Clauses (A/B/C Trusts)
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
When drafting an A/B/C trust, use this sample formula clause to divide the deceased spouse’s assets between the bypass trust and the QTIP trust using a fractional share marital deduction amount. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Checklist: Before You Start Drafting an A/B/C Trust
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Ensure you have considered the critical aspects of the A/B/C trust, and gathered the necessary information from your clients, in order to create a complete and accurate trust draft. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Mastering How A/B/C Trusts Work
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Understand how the typical A/B/C trust operates and how its structure allows for estate tax savings. For further discussion of the tax treatment of A/B/C trusts, see Mitigating Estate Taxes with A/B/C Trusts in the Related Documents section, below.
-
Chart: Is an A/B/C Trust Appropriate?
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Use this chart to assess the various facts and circumstances that may make an A/B/C trust appropriate for your married couple clients, as well as to compare the A/B/C trust structure with the A/B trust structure. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Mitigating Estate Taxes with A/B/C Trusts
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Estate and capital gains tax implications for A/B/C trusts are explained along with illustrations of the strategic advantages available with them. For those less familiar with A/B/C trusts, please first review Mastering How A/B/C Trusts Work in the Related Documents section, below.
-
Sample Distributions from Continuing Trusts After the First Death
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
These sample provisions address distributions from the Survivor’s Trust, Bypass Trust, and QTIP Trust during the surviving spouse’s lifetime. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Selecting Appropriate Accounting Requirements
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Determine the appropriate accounting standard to use in your clients’ trust to address their circumstances, goals, and concerns. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Memorandum of Tangible Personal Property
Trusts & Estates, Estate Planning, Estate Planning for Married Couples, Advanced Tax Planning, Marital Deduction Trusts
Provide this sample memorandum to clients whose trust calls for distribution of tangible personal property in accordance with a Tangible Personal Property Memorandum, whether in whole or in part. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Anticipating Distribution Issues on the Surviving Spouse's Death
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
When drafting the portions of your clients’ revocable trust regarding the distribution after the second spouse’s death, anticipate and address issues that could lead to conflict (and potential litigation). This Strategy Note offers strategic insights for reducing the likelihood that these issues will plague the trust administration.
-
Sample Closing Advice Letter
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Provide your married couple clients with this closing letter to summarize the execution of their estate plan, provide an overview of final instructions, and formally disengage after the matter has concluded. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Standard for Determining Incapacity
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Specify how incapacity will be established—and restored—under the terms of your clients’ trust, avoiding ambiguity, confusion, and potential litigation about a trustee’s ability to act. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Charitable Gifts on Surviving Spouse's Death
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Refer to these sample provisions when making a charitable gift in your clients’ revocable trust to ensure the availability of the charitable deduction (Int.Rev. Code, § 2055) and to minimize the risk of failed charitable gifts. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Certification of Trust
Trusts & Estates, Estate Planning, Estate Planning for Married Couples, Advanced Tax Planning, Marital Deduction Trusts
Use this Certification of Trust to aid your clients in funding their revocable trust, ensuring that they present to their banks and financial institutions the critical information about their trust in a manner that complies with Probate Code section 18100.5. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Duty to Account on Death or Incapacity
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Use these sample provisions to describe under what circumstances the trustee of your clients’ revocable trust must provide an accounting to the trust beneficiaries. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Pecuniary and Specific Gifts After Surviving Spouse's Death
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Use these sample provisions to incorporate pecuniary or specific gifts into your clients’ revocable trust after the second spouse’s death. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample General Assignment
Trusts & Estates, Estate Planning, Estate Planning for Married Couples, Advanced Tax Planning, Marital Deduction Trusts
This general assignment is used to assign your clients’ assets, particularly those without a document of title, into their revocable trust. While assets with a document of title should be formally transferred into the trust (see Trust Funding Memorandum in the Related Documents section, below), general assignments remain an important tool in funding a trust and avoiding probate.
-
Sample Trust Funding Memorandum
Trusts & Estates, Estate Planning, Estate Planning for Married Couples, Qualified Domestic Trusts, Advanced Tax Planning, Marital Deduction Trusts
Use this sample funding memorandum to instruct your married clients on how to formally transfer their assets into their revocable trust. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Chart: When to Consider Including a Trust Protector
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Evaluate when your clients’ goals or circumstances might merit including trust protector provisions in their trust. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Trust Transfer Deed
Trusts & Estates, Estate Planning, Advanced Tax Planning, Marital Deduction Trusts, Real Property Issues in Estate Planning & Administration
Use this Trust Transfer Deed to transfer your clients’ real property into their revocable trust. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Trust Protector Designation and Powers
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
If your trust provides for a trust protector, use this form to designate trust protectors, describe their powers, and limit their liability. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Distributions From Continuing Trusts After the First Death Provisions
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
These sample provisions address distributions from the Survivor’s Trust and Bypass Trust after the first spouse’s death but before the second spouse’s death, including distribution standards applicable to the surviving spouse and optional language to permit distributions to third parties. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Chart: When to Consider Gifting Powers on the Surviving Spouse's Incapacity
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
This chart discusses when you might want to permit trustees to make gifts to third parties after the first spouse’s death. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Beneficiary Designation Memorandum
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Use this sample memorandum to advise your married couple clients on how to properly designate beneficiaries of their accounts in a manner that comports with the clients’ estate plan. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Gifting Powers on the Surviving Spouse’s Incapacity
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Use this form to permit trustees to make gifts to third parties on the surviving spouse’s incapacity. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Determining the Appropriate Funding Formula
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Understand the comparative advantages of selecting either a pecuniary formula or a fractional share formula when drafting the subtrust funding provisions for an A/B trust. For those less familiar with pecuniary formulas and funding options, review the articles in the “Related Documents” section before proceeding.
-
Checklist: Preparing for the Signing Appointment
Trusts & Estates, Estate Planning, Estate Planning for Married Couples, Qualified Domestic Trusts, Advanced Tax Planning, Marital Deduction Trusts
Ensure you have all documents and other information needed for the signing appointment of your married couple clients’ revocable trust. We completed legal editing and analysis of the authorities cited here as of the date listed above.
-
Sample Fractional Share Formula Clauses
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
When drafting an A/B trust, use this sample formula clause to divide the deceased spouse’s assets between the survivor’s trust and bypass trust using a fractional share marital deduction amount. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Pecuniary Formula Clauses (Drafting A/B Trusts)
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
When drafting an A/B trust, use these sample formula clauses to divide the deceased spouse’s assets between the survivor’s trust and bypass trust using a pecuniary marital deduction amount. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Chart: Is an A/B Trust Appropriate?
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Use this chart to assess the various facts and circumstances that may make an A/B trust appropriate for your married couple clients. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Mastering How A/B Trusts Work
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Understand how the typical A/B trust operates and how its structure allows for estate tax savings. For further discussion of the tax treatment of A/B trusts, see Mitigating Estate Taxes with A/B Trusts in the Related Documents section, below.
-
Checklist: Before You Start Drafting an A/B Trust
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Ensure you have considered the critical aspects of the A/B trust, and gathered the necessary information from your clients, in order to create a complete and accurate trust draft. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Transmittal Letter to Clients With Draft A/B Trust
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Use this letter to ensure your clients are adequately informed of the critical elements of their draft estate planning documents, including their A/B trust, wills, powers of attorney for health care and financial affairs, and other ancillary documents. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Schedule of Assets
Trusts & Estates, Estate Planning, Estate Planning for Married Couples, Advanced Tax Planning, Marital Deduction Trusts
This sample Schedule of Assets identifies the assets to be held in your married couple clients’ trust, including characterization of such assets. We completed legal editing and analysis of authorities cited here as of the date listed below
-
Mitigating Estate Taxes with A/B Trusts
Trusts & Estates, Estate Planning, Estate Planning for Married Couples
Estate and capital gains tax implications for A/B trusts are explained along with illustrations of the strategic advantages available with them. For those less familiar with A/B trusts, please first review How A/B Trusts Work in the Related Documents section, below.
-
Leveraging Use of Self-Canceling Installment Notes (SCINs) in Business Succession Planning
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
Evaluate the use of self-canceling installment notes (SCINs) in business succession planning. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Mastering the Federal Gift and Estate Tax System
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
This Strategy Note explains the United States federal transfer tax system, including estate, gift, and generation-skipping transfer tax, as applied to United States citizens and residents. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Documents Needed for Valuation
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
Ensure you gather the documentation needed for valuing a client’s business for succession planning purposes. While the documents needed in a particular case may vary depending on the nature of the business at issue, the documents listed below should provide sufficient background to begin the valuation process.
-
Business Information and Succession Intake Information
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
Collect information during an initial client meeting with an estate planning client who has business succession issues. The client’s responses will help indicate the depth of exploration needed for each topic area.
-
How to Petition for Appointment of Conservator
Trusts & Estates, Guardianships & Conservatorships, Appointment of Conservatorship
Use this How-To Guide to petition for appointment of a conservator of the person and/or estate. Carefully research and adapt the following material to the facts and circumstances of your matter and verify the currentness of the legal authorities.
-
Knowing When to Account (Establishing Conservatorships)
Trusts & Estates, Guardianships & Conservatorships, Administration of the Conservatee's Estate, Conservatorship and Guardianship Accounting
This Strategy Note discusses the circumstances under which a conservator is required to prepare and file an accounting, as well as when a conservator might elect to prepare an accounting even when doing so is not required. Carefully research and adapt the following material to the facts and circumstances of your matter and verify the currentness of the legal authorities.
-
Understanding Priority of Payment of Debts (Establishing Conservatorships)
Trusts & Estates, Guardianships & Conservatorships, Administration of the Conservatee's Estate, Powers and Limitations for the Conservator of the Person
Use this Strategy Note to understand the priority of the payment of debts when establishing a conservatorship. Carefully research and adapt the following material to the facts and circumstances of your matter and verify the currency of the legal authorities.
-
Sample Petition to Approve Conservator's Account
Trusts & Estates, Guardianships & Conservatorships, Administration of the Conservatee's Estate, Conservatorship and Guardianship Accounting
Use this petition to seek court approval of a conservator’s account. The following standard document is for illustrative purposes only and should not be used without careful research and adaptation for the facts and circumstances of the instant case or matter.
-
How to Use a Charitable Gift Deduction for Estate and Gift Tax Savings
Trusts & Estates, Advanced Tax Planning, Charitable Remainder Trusts, Charitable Lead Trusts
Clients can achieve gift and estate tax savings by making transfers to qualified charitable organizations both during life and after death. This document explains how to take advantage of the transfer tax deductions available for such transfers.
-
Prepare a Fiduciary Income Tax Return (IRS Form 1041)
Trusts & Estates, Advanced Tax Planning, Administering Trusts for High-Net-Worth Clients
Use this guide to understand the basic and necessary steps for filing a U.S. Income Tax Return for Estates and Trusts (Form 1041). Please remember, this is a general description of how to prepare a trust income tax return.
-
Comparing True Worth, Fairly Representative and Minimum Worth Funding Within the Pecuniary Formula (Estate Planning)
Trusts & Estates, Advanced Tax Planning, Administering Trusts for High-Net-Worth Clients
This document compares the true worth, fairly representative, and minimum worth funding methods. These methods are used in conjunction with A/B or A/B/C trusts that use a pecuniary formula for marital deduction trust funding.
-
Calculating the GRAT Gift Value
Trusts & Estates, Advanced Tax Planning, Administering Trusts for High-Net-Worth Clients
Calculate the gift value of a single settlor Grantor Retained Annuity Trust for gift and estate tax purposes through a step-by-step process. It contains an optional step to calculate the estimated amount that will pass to beneficiaries free of gift tax based on an assumed rate of return on GRAT assets.
-
Use a Split-Gift Election for Estate and Gift Tax Savings
Trusts & Estates, Advanced Tax Planning, Estate Tax Planning Strategies, Additional Tax Considerations & Strategies, Specific Irrevocable Trust Strategies
Brief your client on the split-gift election and using the election to maximize transfer tax savings. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Advising on Retirement Plan Beneficiary Designation After SECURE 2.0
Trusts & Estates, Advanced Tax Planning, Estate Tax Planning Strategies, Retirement Planning
Carefully advise clients on whom to designate as beneficiary of their IRAs after enactment of the SECURE 2.0 Act of 2022 (part of the Consolidated Appropriations Act, 2023 (H.R. 2617).) We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Maximizing Tax Savings Using a Irrevocable Life Insurance Trust
Trusts & Estates, Advanced Tax Planning, Estate Tax Planning Strategies, Retirement Planning
This document discusses how irrevocable life insurance trusts (ILITs) can be used to minimize estate taxes. For complete sample ILIT forms, see Drafting California Irrevocable Trusts §§20.5–20.8.
-
Use a Conduit Trust for IRA Tax Savings (Estate Planning)
Trusts & Estates, Advanced Tax Planning, Additional Tax Considerations & Strategies, Specific Irrevocable Trust Strategies
Use conduit trusts to minimize income taxes related to individual retirement account (IRA) withdrawals after enactment of SECURE 2.0 Act of 2022 (part of the Consolidated Appropriations Act, 2023 (H.R. 2617).) We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Strategies to Maximize Capital Gains Tax Savings (Estate Planning)
Trusts & Estates, Advanced Tax Planning, Estate Tax Planning Strategies, Additional Tax Considerations & Strategies
Review strategies for avoiding capital gains tax when designing and administering estate plans. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Like-Kind Exchanges of Real Property Under Internal Revenue Code Section 1031
Trusts & Estates, Advanced Tax Planning, Estate Tax Planning Strategies, Additional Tax Considerations & Strategies
Use like-kind exchanges of real property under Internal Revenue Code section 1031 to defer capital gains tax. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Understanding the Tax Implications of Appointing Property (Estate Planning)
Trusts & Estates, Advanced Tax Planning, Additional Tax Considerations & Strategies
This document explains general and limited powers of appointment, as well as the tax implications related to their use. Carefully research and adapt the following material to the facts and circumstances of your matter and verify the currentness of the legal authorities.
-
Tax Strategies for Dividing Property of an A/B/C Trust at the First Death (Estate Planning)
Trusts & Estates, Estate Planning, Estate Planning for Married Couples, Advanced Tax Planning, Estate Tax Planning Strategies, Additional Tax Considerations & Strategies
This Strategy Note discusses tax strategies and considerations for the allocation of assets in an A/B/C trust structure, where assets are divided between a survivor’s trust, bypass trust, and marital trust. Carefully research and adapt the following material to the facts and circumstances of your matter and verify the currentness of the legal authorities.
-
Tax Strategies for Division Property of an A/B Trust at the First Death (Estate Planning)
Trusts & Estates, Advanced Tax Planning, Estate Tax Planning Strategies, Additional Tax Considerations & Strategies
This Strategy Note discusses tax strategies and considerations when allocating assets between the survivor’s trust and bypass trust at the first settlor’s death. Carefully research and adapt the following material to the facts and circumstances of your matter and verify the currentness of the legal authorities.
-
Understanding the Marital Deduction Fractional Share Formula (Estate Planning)
Trusts & Estates, Estate Planning, Estate Planning for Married Couples, Advanced Tax Planning, Estate Tax Planning Strategies, Additional Tax Considerations & Strategies
This document provides an explanation of the marital deduction fractional share formula and the funding methods by which the formula may be carried out. Carefully research and adapt the following material to the facts and circumstances of your matter and verify the currentness of the legal authorities.
-
Understanding the Marital Deduction Pecuniary Formula (Estate Planning)
Trusts & Estates, Estate Planning, Estate Planning for Married Couples, Advanced Tax Planning, Estate Tax Planning Strategies, Additional Tax Considerations & Strategies
This document provides an explanation of the marital deduction pecuniary formula and the funding methods by which the formula may be carried out. Carefully research and adapt the following material to the facts and circumstances of your matter and verify the currentness of the legal authorities.
-
Understanding the Generation Skipping Transfer Tax for High Net Worth Estates
Trusts & Estates, Advanced Tax Planning, Estate Tax Planning Strategies, Additional Tax Considerations & Strategies
This Strategy Note explains the generation-skipping transfer (GST) tax, including when GST tax applies and how it is calculated. Carefully research and adapt the following material to the facts and circumstances of your matter and verify the currentness of the legal authorities.
-
Understanding the Taxation of A/B Marital Trusts (Estate Planning)
Trusts & Estates, Estate Planning, Estate Planning for Married Couples, Advanced Tax Planning, Estate Tax Planning Strategies, Additional Tax Considerations & Strategies
This Strategy Note explains the estate and capital gains tax implications of A/B trust structures, often referred to as “mandatory bypass trust” or simply “bypass trust” structures. Carefully research and adapt the following material to the facts and circumstances of your matter and verify the currentness of the legal authorities.
-
Mastering the Taxation of A/B/C Trusts (Estate Planning)
Trusts & Estates, Estate Planning, Estate Planning for Married Couples, Advanced Tax Planning, Estate Tax Planning Strategies, Additional Tax Considerations & Strategies
Master the estate and capital gains tax implications of A/B/C trust structures, often referred to as “QTIP trust” structures. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Understanding IRS Appraisal Requirements for Unique Assets (Estate Planning)
Trusts & Estates, Advanced Tax Planning, Estate Tax Planning Strategies, Additional Tax Considerations & Strategies
This Strategy Note discusses the Internal Revenue Service’s valuation requirements for unique assets such as collectibles, intangible property, and closely held businesses when reporting these assets on a decedent’s estate tax return. Carefully research and adapt the following material to the facts and circumstances of your matter and verify the currentness of the legal authorities.
-
Chart: Eligible and Ineligible Beneficiaries for Retirement Plans (Estate Planning)
Trusts & Estates, Estate Planning, Advanced Tax Planning
The following chart summarizes the IRS rules regarding beneficiaries of defined-contribution plans and their consequent payout rules post-SECURE Act. Carefully research and adapt the following material to the facts and circumstances of your matter and verify the currentness of the legal authorities.
-
Chart: California Property Tax Reassessment Exclusions and Filing Requirements
Trusts & Estates, Estate Planning, Real Property Tax Reassessment, Advanced Tax Planning, Estate Tax Planning Strategies
Refer to the following chart for a summary of important rules, exclusion qualification requirements, and statutes regarding reassessment for property tax purposes following the passage of Proposition 19 (now codified as Rev. & Tax. Code, § 63.2). We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Strategies to Avoid Reassessment of Real Property at Transfer
Trusts & Estates, Advanced Tax Planning, Additional Tax Considerations & Strategies
This Strategy Note discusses strategic considerations for avoiding property tax reassessment on the transfer of real property. Carefully research and adapt the following material to the facts and circumstances of your matter and verify the currentness of the legal authorities.
No programs found.
No secondary sources available.
Scroll to TopCopy the link below: