CEB Contributor
Christina M. Chan
Content Attorney at Continuing Education of the Bar (CEB)
Christina Chan is a content attorney for CEB. She has almost a decade of experience in estate planning and administration, as well as several years of experience practicing bankruptcy law.
Prior to joining CEB, Ms. Chan was an attorney at Falcon Rappaport & Berkman LLP, where she counseled clients on maximizing generational wealth by implementing sophisticated strategies to reduce estate taxes and protect assets from creditors. Previously, she worked as an attorney at several boutique firms in Orange County, California, where her practice encompassed high-net worth estate planning, trust administration, business and real estate transactions, and trust and probate litigation matters. Before this, Ms. Chan was an attorney at a bankruptcy firm where she represented hundreds of debtors, creditors, and Chapter 7 trustees. Ms. Chan earned her BA in Economics from the University of California, Los Angeles, and her J.D. from Loyola Law School, Los Angeles.
CEB Region:
Bay Area RegionPractice Areas:
Trusts & Estates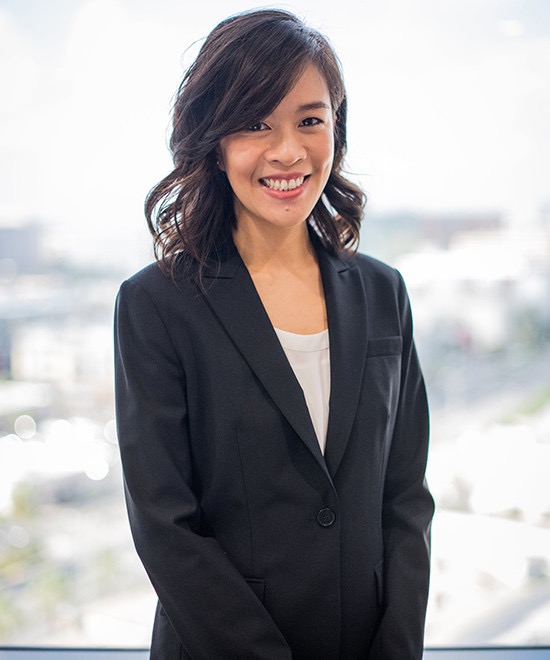
Content by Christina M. Chan
-
Why Precise Drafting Matters: Fourth District Clarifies Limits of Equalization Provisions in Trust Agreements
November 2, 2026
Christina M. Chan
Trusts & Estates, Estate Planning, Estate Planning for Married Couples, Estate Planning for Singles
Trust agreements are frequently designed to include equalization provisions, which ensure that children or other beneficiaries receive equal shares of a settlor’s wealth. These provisions often instruct the trustee to account for lifetime gifts, loans or other financial benefits previously provided to certain beneficiaries when determining their share of the trust estate. However, as a recent California appellate decision demonstrates, the way the language is drafted can significantly affect how trust assets are ultimately distributed.
A Recent Bankruptcy Court Case Holds Key Asset Protection Lessons
September 17, 2026
Christina M. Chan
Bankruptcy, Trusts & Estates
In
Estate of Spenlinhauer: Practical Lessons in Estate Planning Maintenance and Administration
August 4, 2026
Christina M. Chan
Tax Law, Trusts & Estates, Trust Administration, Distributions from the Trust, Initial Post-Death Administration, Long Term Trust Administration
The recent U.S. Tax Court decision in
The Overdeck Litigation: Risk Management Lessons for Estate Planners Representing Married Couples
June 25, 2026
Christina M. Chan
Family Law, Legal Ethics, Trusts & Estates, Estate Planning, Estate Planning for Married Couples
A high-profile dispute arising from the divorce of hedge fund billionaire John Overdeck and his wife, Laura Overdeck, provides a useful reminder that some of the most significant risks facing estate planning attorneys representing married couples (particularly in sophisticated wealth transfer and asset protection matters) do not arise from creditor challenges, IRS disputes or drafting errors. Rather, these risks are embedded in fundamental professional responsibility issues that estate planners encounter on a day-to-day basis: who the client is in a joint representation; whether the material consequences of a planning strategy have been adequately disclosed; and whether informed written consent has been obtained when the planning when the interests of one spouse may be adversely impacted by the proposed planning.
Avoiding Waiver of the Attorney-Client Privilege and Work Product Protection When Using Generative AI Tools
May 12, 2026
Christina M. Chan
Business Transactions, Law Practice Management, Legal Ethics, Privacy & Information Security, Types of Privacy Protections, Workplace Privacy, Financial Data Privacy, Internet and Electronic Privacy
While attorneys are increasingly using artificial intelligence tools to assist with drafting, research and analysis, the legal profession’s rapid integration of generative artificial intelligence raises a critical issue: whether disclosing client information to these tools risks waiving the attorney-client privilege and work product protections.
U.S. v. Huckaby: A Spring Cleaning Reminder for Your Clients’ Estate Plans
March 31, 2026
Christina M. Chan
Tax Law, Trusts & Estates, Estate Planning, Estate Planning for Unmarried Couples, Estate Planning for Married Couples, Estate Planning for Singles, Advanced Tax Planning, Estate Tax Planning Strategies
The recent decision in
Estate of Griffin v. Commissioner: When Intent to Provide for a Surviving Spouse Isn’t Enough to Avoid Tax Heartbreak
February 17, 2026
Christina M. Chan
Tax Law, Trusts & Estates, Estate Planning, Estate Planning for Married Couples
The recent U.S. Tax Court decision in
Holiday Generosity or Enforceable Loan? Intrafamily Transfers in Light of Estate of Galli
January 5, 2026
Christina M. Chan
Tax Law, Trusts & Estates, Estate Planning, Inter-Vivos Gifting, Advanced Tax Planning, Additional Tax Considerations & Strategies
Intrafamily loans continue to be an area of close scrutiny by the IRS. As discussed in a
Wrap Up Your Charitable Gifts By the End of 2025: New OBBBA Rules Make This the Season to Gift
November 24, 2025
Christina M. Chan
Tax Law, Trusts & Estates, Estate Planning, Charitable Gifting, Inter-Vivos Gifting, Advanced Tax Planning, Charitable Lead Trusts, Additional Tax Considerations & Strategies
The federal One Big Beautiful Bill Act (OBBBA), which takes effect Jan. 1, 2026, introduces numerous changes to federal law, including updates to the federal charitable deduction rules. As we enter the holiday season, 2025 presents important planning opportunities for donors who wish to maximize charitable deductions before the new law takes effect.
Estate of Rowland v. Commissioner: A Halloween Horror Story About Portability Elections
October 14, 2025
Christina M. Chan
Tax Law, Trusts & Estates, Estate Planning, Estate Planning for Married Couples, Advanced Tax Planning, Estate Tax Planning Strategies, Additional Tax Considerations & Strategies
The recent U.S. Tax Court decision in
Revisiting SLATs in 2025: Expanding Opportunities and Evolving Uses
September 3, 2025
Christina M. Chan
Family Law, Trusts & Estates, Advanced Tax Planning, Estate Tax Planning Strategies, Additional Tax Considerations & Strategies, Specific Irrevocable Trust Strategies
Spousal Lifetime Access Trusts (SLATs) have become a staple of advanced estate planning—especially for married couples seeking to reduce estate tax liability while preserving some level of indirect access to the transferred assets. The core idea behind a SLAT is straightforward: one spouse gifts assets to an irrevocable trust that benefits the other spouse (and potentially other beneficiaries), allowing those assets and their appreciation to escape future estate taxation if structured as a completed gift trust.
Estate Planning in a Shifting Market: Strategies for Uncertain Times
April 29, 2025
Christina M. Chan
Trusts & Estates, Advanced Tax Planning, Grantor Retained Annuity Trusts, Intentionally Defective Grantor Trusts, Estate Tax Planning Strategies, Additional Tax Considerations & Strategies, Specific Irrevocable Trust Strategies
While market volatility can be unsettling for many, it presents a unique opportunity to advise clients on sophisticated estate planning strategies that may be especially advantageous during periods of uncertainty. Deflated asset values and fluctuating interest rates present conditions that, if leveraged properly, can offer significant transfer tax savings and long-term wealth preservation. Below are some key estate planning techniques to consider during economic downturns or market turbulence.
New IRS Ruling Highlights the Hidden Capital Gains Tax Risks of Early Trust Terminations
March 25, 2025
Christina M. Chan
Tax Law, Trusts & Estates, Advanced Tax Planning, Additional Tax Considerations & Strategies
The Internal Revenue Service's
Essential High-Net-Worth Estate Planning Tips for 2025
February 4, 2025
Christina M. Chan
Insurance Law, Real Property, Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses, Advanced Tax Planning
The first months of a new year provide a fresh opportunity to plan and adjust for the year ahead. Below are some important considerations to help ensure that your California clients’ estate plans are as effective as possible in 2025, particularly in light of a new presidential administration and last month's wildfires in Los Angeles.
Liability for Unpaid Estate Taxes Could Haunt Trustees and Beneficiaries for Years. How Should You Advise Those Clients?
December 26, 2024
Christina M. Chan
Tax Law, Trusts & Estates, Trust Administration, Distributions from the Trust, Long Term Trust Administration, Advanced Tax Planning, Additional Tax Considerations & Strategies, Administering Trusts for High-Net-Worth Clients
Can a successor trustee or beneficiary be held personally liable for unpaid estate taxes owed by the settlor’s estate? What if the successor trustee is appointed several years after the settlor’s death? Read on to learn the Ninth Circuit's answer to these questions -- and how to accordingly advise clients who are considering accepting an appointment as a successor trustee.
California Will Significantly Reduce Creditor Protections for Certain Tax-Qualified Retirement Plans in 2025
November 12, 2024
Christina M. Chan
Litigation Practice & Procedure, Judgments & Verdicts, Judgment Enforcement, Trusts & Estates, Estate Planning, Asset Protection (Spendthrift) Trusts
On September 24, California Gov. Gavin Newsom signed
U.S. Tax Court: Commutation of QTIP Trust Is a Taxable Gift by Remainder Beneficiaries to Surviving Spouse
October 2, 2024
Christina M. Chan
Tax Law, Trusts & Estates, Estate Planning, Estate Planning for Married Couples, Advanced Tax Planning, Estate Tax Planning Strategies, Additional Tax Considerations & Strategies, Administering Trusts for High-Net-Worth Clients
On September 23, the U.S. Tax Court unanimously held in
Intrafamily Loans: When Treating Family Like Strangers Is a Good Thing
August 20, 2024
Christina M. Chan
Tax Law, Trusts & Estates, Estate Planning, Advanced Tax Planning
While intrafamily loans are important tools that can be used to transfer wealth to the next generation, most parents are unaware that their actions and expectations with respect to repayment of the loan can transmute the loan into a gift, resulting in unintended gift and estate tax consequences. This is exactly what happened to Mary Bolles in a Tax Court opinion that was recently
How the Supreme Court's Decision in Connelly v. U.S. Directly Impacts Business Owners and Their Estates
July 8, 2024
Christina M. Chan
Tax Law, Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
On June 6, in
Trustees and Beneficiaries Beware: Think Twice Before Modifying an Irrevocable Trust
May 27, 2024
Christina M. Chan
Trusts & Estates, Estate Planning, Trust Administration, Advanced Tax Planning
Under section 6110(i)(1) of the Internal Revenue Code, a Chief Counsel Advice memorandum (“CCA”) is a term used to describe written advice or instruction issued by the Service or the Office of Chief Counsel to field offices concerning the IRS’ legal interpretations or positions on existing or former revenue provisions. While CCAs do not have precedential value, they are required to be released to the public for the purpose of providing taxpayers with the views of personnel of the Office of Chief Counsel as to current tax issues.
When California Gives Taxpayers Lemons, Make Lemonade: What To Do with ING Trusts Now That They're Obsolete in California
April 15, 2024
Christina M. Chan
Tax Law, Trusts & Estates, Estate Planning, Asset Protection (Spendthrift) Trusts, Advanced Tax Planning, Estate Tax Planning Strategies, Additional Tax Considerations & Strategies, Specific Irrevocable Trust Strategies
On July 10, 2023, California
-
Sample Affidavit of Solvency (Asset Protection Strategies for California Residents)
Trusts & Estates, Estate Planning, Asset Protection Strategies for California Residents
Use this Sample Affidavit of Solvency to help mitigate the risk of becoming inadvertently involved in a client’s voidable transaction or fraudulent transfer dispute by documenting the source of the assets used to fund the trust and the client’s representations regarding any pending, threatened, or anticipated litigation. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Exploring the Use of Irrevocable Trusts in California Asset Protection Planning
Trusts & Estates, Estate Planning, Asset Protection Strategies for California Residents
Gain strategic insights into irrevocable trust strategies that afford asset protection benefits. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Complete a Preliminary Change of Ownership Report for a Real Property Transfer to a Legal Entity (Real Property Tax Reassessment)
Trusts & Estates, Estate Planning, Real Property Tax Reassessment
Complete a Preliminary Change of Ownership Report (PCOR) when transferring real property to a legal entity. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Report a Change in Control or Change in Ownership of a Legal Entity to the State Board of Equalization (Real Property Tax Reassessment)
Trusts & Estates, Estate Planning, Real Property Tax Reassessment
This guide discusses the procedure for completing and filing a Statement of Change in Control and Ownership of Legal Entities (Form BOE-100-B) with the State Board of Equalization. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Determine Whether Transfers Involving Legal Entities Will Trigger California Property Tax Reassessment (Real Property Tax Reassessment)
Trusts & Estates, Estate Planning, Real Property Tax Reassessment
Use this guide to understand how legal entity transfers may cause the underlying real property to be reassessed for property tax purposes, and how to determine if such transfer will result in reassessment of the property. For an in-depth discussion of property tax issues as they relate to estate planning, see California Estate Planning chapter 15.
-
Complete Form BOE-19-P or BOE-19-G to Claim the Parent-Child or Grandparent-Grandchild Exclusion (Real Property Tax Reassessment)
Trusts & Estates, Estate Planning, Real Property Tax Reassessment
This guide discusses the procedure for completing the Claim for Reassessment Exclusion for Transfer Between Parent and Child Occurring On Or After February 16, 2021 (Form BOE-19-P) or Claim for Reassessment Exclusion for Transfer Between Grandparent and Grandchild Occurring On Or After February 16, 2021 (Form BOE-19-G). We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Deed for Parent-Child or Grandparent-Grandchild Transfers (Real Property Tax Reassessment)
Trusts & Estates, Estate Planning, Real Property Tax Reassessment
This sample deed can be used when effectuating a real property transfer between parent(s) and child(ren) or grandparent(s) and grandchild(ren) (or to a trust for their benefit). We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Draft and Record Deeds for Parent-Child and Grandparent-Grandchild Transfers (Real Property Tax Reassessment)
Trusts & Estates, Estate Planning, Real Property Tax Reassessment
Use this guide when effectuating a real property transfer between parent(s) and child(ren) or grandparent(s) and grandchild(ren). We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Evaluate and Claim the Parent-Child or Grandparent-Grandchild Exclusion (Real Property Tax Reassessment)
Trusts & Estates, Estate Planning, Real Property Tax Reassessment
Develop a comprehensive understanding of how intergenerational real property transfers between a parent and child or between a grandparent and a grandchild may cause property taxes to be reassessed and how to claim the parent-child or grandparent-grandchild exclusion from reassessment. This guide applies to transfers of real property occurring on or after February 16, 2021, the applicable date of changes made by Proposition 19.
-
Before You Start Drafting a QDOT (Qualified Domestic Trusts)
Trusts & Estates, Estate Planning, Qualified Domestic Trusts
Use this checklist before you start drafting a revocable trust that incorporates qualified domestic trust (QDOT) provisions to help ensure that you have the necessary information about your client and their wishes. For a more detailed discussion of QDOTs, see Drafting California Revocable Trusts (4th ed Cal CEB) §§ 13.27–13.35.
-
Using a Qualified Domestic Trust to Preserve the Unlimited Marital Deduction for a Non-Citizen Spouse (Qualified Domestic Trusts)
Trusts & Estates, Estate Planning, Qualified Domestic Trusts
Gain strategic insight into how a non-citizen spouse can qualify for the unlimited marital deduction by using a qualified domestic trust (QDOT). For an in-depth discussion of QDOTs, see California Will Drafting, §§19.33-19.41 and Drafting California Revocable Trusts, §§ 13.27-13.35.
-
Comparing General Power of Appointment Trusts with QTIP Trusts (Marital Deduction Trusts)
Trusts & Estates, Advanced Tax Planning, Marital Deduction Trusts
Refer to the following chart to compare general power of appointment (GPOA) trusts with qualified terminable interest property (QTIP) trusts, which are two primary types of marital deduction trusts used to receive the marital share of the deceased spouse’s property at their passing while qualifying for the unlimited marital deduction. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Transmittal Letter to Married Clients with Draft Revocable Trust (Marital Deduction Trusts)
Trusts & Estates, Advanced Tax Planning, Marital Deduction Trusts
Use this letter to ensure your married couple clients are adequately informed of the salient provisions of their revocable trust and other draft estate planning documents, including their pour-over wills, funding documents, and other ancillary documents. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Closing Letter to Clients (Marital Deduction Trusts)
Trusts & Estates, Advanced Tax Planning, Marital Deduction Trusts
Provide your married couple clients with this closing letter to summarize the salient terms of their estate plan (including a revocable trust that establishes a marital trust at the death of the first spouse), provide an overview of final instructions, and formally terminate the representation of the clients after the matter has concluded. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Transfer Real Property and Financial Accounts to a Revocable Trust (Marital Deduction Trusts)
Trusts & Estates, Advanced Tax Planning, Marital Deduction Trusts
Use this guide when transferring real property and financial accounts to a revocable trust settled by your married or registered domestic partner clients. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Complete a Preliminary Change of Ownership Report (PCOR) for a Real Property Transfer to a Jointly Settled Revocable Trust (Marital Deduction Trusts)
Trusts & Estates, Advanced Tax Planning, Marital Deduction Trusts
Use this guide to complete a Preliminary Change of Ownership Report (PCOR) in connection with a real property transfer by married clients to their jointly settled revocable trust. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
File Closing Checklist (Marital Deduction Trusts)
Trusts & Estates, Advanced Tax Planning, Marital Deduction Trusts
You may use this checklist when closing your married couple client’s file after completing work on their estate plan (including a revocable trust that establishes a marital trust at the death of the first spouse). This checklist assumes that you have handled the execution and funding of the trust but are not involved with its administration.
-
Sample Clayton QTIP Provisions (Marital Deduction Trusts)
Trusts & Estates, Advanced Tax Planning, Marital Deduction Trusts
Use this sample language when drafting revocable living trust in which the deceased settlor’s property may be allocated between the bypass and QTIP trusts at the deceased settlor’s death through a Clayton election made for all or a portion of such property. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Pecuniary Amount Formula Language (Marital Deduction Trusts)
Trusts & Estates, Advanced Tax Planning, Marital Deduction Trusts
Use these sample clauses when dividing the deceased spouse’s assets between the marital share and the nonmarital share using a pecuniary amount. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Fractional Share Formula Language (Marital Deduction Trusts)
Trusts & Estates, Advanced Tax Planning, Marital Deduction Trusts
Use this sample clause when dividing the deceased spouse’s assets between the marital share and the nonmarital share using a fractional share amount. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Chart Comparing Charitable Lead Annuity Trust (CLAT) with Charitable Lead Unitrust (CLUT)
Trusts & Estates, Advanced Tax Planning, Charitable Lead Trusts
Refer to the following chart to compare charitable lead annuity trusts (CLATs) with charitable lead unitrusts (CLUTs), which are two primary types of charitable lead trusts (CLTs). We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Letter to Financial Institution Requesting Transfer of Assets to CLT
Trusts & Estates, Advanced Tax Planning, Charitable Lead Trusts
This sample letter may be used to request the transfer of a client’s individual financial assets into an account at the same financial institution in the name of the trustee of a charitable lead trust (CLT) settled by the client. This sample assumes that the trustee of the CLT has already opened a new trust account in the name of the trustee of the CLT.
-
File Closing Checklist (CLTs)
Trusts & Estates, Advanced Tax Planning, Charitable Lead Trusts
You may use this checklist when closing a client’s file after completing work on their charitable lead trust (CLT). This checklist assumes that you have handled the execution and funding of the trust but are not involved with its administration until the CLT term expires.
-
Sample Letter to County Recorder’s Office Requesting Recordation of Deed Transferring Real Property to CLT
Trusts & Estates, Advanced Tax Planning, Charitable Lead Trusts
This sample letter may be used to request that the county recorder’s office record a deed transferring real property to the trustee of a charitable lead trust (CLT). Fees should be attached as determined by the specific county’s fee schedule.
-
Sample Deed Transferring Real Property to a CLT
Trusts & Estates, Advanced Tax Planning, Charitable Lead Trusts
This sample deed can be used when a client transfers real property to a charitable lead trust (CLT). You may modify this as needed to conform to the facts of your particular matter.
-
Checklist for CLT Execution
Trusts & Estates, Advanced Tax Planning, Charitable Lead Trusts
Refer to this checklist to confirm you have all the necessary documents and information for the signing appointment with your client establishing a charitable lead trust (CLT). We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Transfer Real Property and Financial Accounts to a CLT
Trusts & Estates, Advanced Tax Planning, Charitable Lead Trusts
Use this guide when transferring real property and financial accounts to a charitable lead trust (CLT). We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Transfer a Business Interest to a CLT
Trusts & Estates, Advanced Tax Planning, Charitable Lead Trusts
Use this guide when transferring a business interest to a charitable lead trust (CLT). We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Transmittal Letter to Client with Draft CLT
Trusts & Estates, Advanced Tax Planning, Charitable Lead Trusts
This sample letter may be used to accompany the draft of a single settlor charitable lead trust sent to your client for review. It offers a brief overview of the trust, outlining key elements such as its structure and dispositive provisions to ensure that the trust conforms with the client’s tax and estate planning goals.
-
Identifying the Client’s Business Succession Planning Objectives
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
Use this checklist to help elicit information from the client regarding their business succession planning objectives. You may work the questions into the initial meeting with the client as a means to guide the conversation.
-
File Closing Checklist (SLATs)
Trusts & Estates, Advanced Tax Planning, Spousal Lifetime Access Trusts
You may use this checklist when closing a client’s file after completing work on their spousal lifetime access trust (SLAT). This checklist assumes that you have handled the execution and funding of the trust but are not involved with its administration.
-
Sample SLAT Administration Memo to Client
Trusts & Estates, Advanced Tax Planning, Spousal Lifetime Access Trusts
This is a sample memorandum addressed to the client which outlines the administration of the spousal lifetime access trust established by the client. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Deed of Gift Transferring a Business Interest to a SLAT
Trusts & Estates, Advanced Tax Planning, Spousal Lifetime Access Trusts
This sample Deed of Gift may be used when the client makes an inter vivos gift of an interest in their business to a spousal lifetime access trust (SLAT) settled by the client. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Deed Transferring Real Property to a SLAT
Trusts & Estates, Advanced Tax Planning, Spousal Lifetime Access Trusts
This sample deed can be used by single, married or registered domestic partner clients when transferring real property to a spousal lifetime access trust (SLAT) settled by the client. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Letter to County Recorder’s Office Requesting Recordation of Deed (SLAT)
Trusts & Estates, Advanced Tax Planning, Spousal Lifetime Access Trusts
This sample letter may be used to request that the county recorder’s office record a deed transferring real property to the trustee of a spousal lifetime access trust (SLAT). Fees should be attached as determined by the specific county’s fee schedule.
-
Preparing for the Signing Appointment (SLATs)
Trusts & Estates, Advanced Tax Planning, Spousal Lifetime Access Trusts
Refer to this checklist to confirm you have all the necessary documents and information for the signing appointment with your client establishing a spousal lifetime access trust (SLAT). We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Transmittal Letter to Client With Draft SLAT
Trusts & Estates, Advanced Tax Planning, Spousal Lifetime Access Trusts
This sample letter may be used to accompany the draft of a spousal lifetime access trust (SLAT) sent to the client for review. It offers a brief overview of the trust, highlighting key elements such as its purpose, dispositive provisions, and the client’s responsibilities, to ensure that the trust aligns with the client’s estate planning goals.
-
Before You Start Drafting a SLAT (Checklist)
Trusts & Estates, Advanced Tax Planning, Spousal Lifetime Access Trusts
Use this checklist before you start drafting a spousal lifetime access trust (SLAT) to ensure that you have the necessary information about your client and their wishes. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Advice and Warning Letter to Client (SLATs)
Trusts & Estates, Advanced Tax Planning, Spousal Lifetime Access Trusts
This sample letter may be used when counseling clients about the benefits, drawbacks, and potential risks associated with implementing a spousal lifetime access trust (SLAT). By understanding how this trust works and its implications, the client can make a more informed decision about whether it aligns with their long-term financial and estate planning objectives.
-
Sample Advice and Warning Letter to Client (QPRTs)
Trusts & Estates, Advanced Tax Planning, Qualified Personal Residence Trusts
This sample letter may be used when counseling clients about the benefits, drawbacks, and potential risks associated with implementing a qualified personal residence trust. By understanding how this trust works and its implications, the client can make a more informed decision about whether it aligns with their long-term financial and estate planning objectives.
-
File Closing Checklist (QPRTs)
Trusts & Estates, Advanced Tax Planning, Qualified Personal Residence Trusts
You may use this checklist when closing a client’s file after completing work on their qualified personal residence trust (QPRT). This checklist assumes that you have handled the execution and funding of the trust but are not involved with its administration until the trust term ends.
-
Closing Letter to Client – Completion of QPRT
Trusts & Estates, Advanced Tax Planning, Qualified Personal Residence Trusts
This sample letter may be used to commemorate the completion of work relating to the establishment and initial funding of a client’s qualified personal residence trust, and to terminate the representation of such client until further work is needed. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Attorney Drafted Form of Power of Attorney for Financial Management
Trusts & Estates, Estate Planning, Powers of Attorney for Financial Management
Use this attorney-drafted power of attorney for financial management as a component of a complete estate plan to allow a client to designate a financial decision maker to assist with management of their financial affairs. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Certificate of Trust (QPRT)
Trusts & Estates, Advanced Tax Planning, Qualified Personal Residence Trusts
This sample certificate of trust may be used to verify the existence of a qualified personal residence trust (QPRT) and provide key details about its terms, without disclosing the full trust agreement. This certificate of trust allows your clients to present to their banks and financial institutions the critical information about their trust in a manner that complies with Probate Code section 18100.5.
-
Sample Transmittal Letter to Client with Draft QPRT
Trusts & Estates, Advanced Tax Planning, Qualified Personal Residence Trusts
This sample letter may be used to accompany the draft of a qualified personal residence trust (QPRT) sent to the client for review. It offers a brief overview of the trust, highlighting key elements such as its purpose, the trust term, and dispositive provisions, to ensure that the trust aligns with the client’s estate planning goals.
-
Fund the QPRT
Trusts & Estates, Advanced Tax Planning, Qualified Personal Residence Trusts
Use this guide when transferring real property and cash to a qualified personal residence trust (QPRT). We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Is a QPRT Right for Your Client?
Trusts & Estates, Advanced Tax Planning, Qualified Personal Residence Trusts
When considering a qualified personal residence trust (QPRT) for a client’s estate planning strategy, it is important to evaluate the client’s unique financial and personal circumstances to determine if it is an appropriate estate planning tool. Use this guide to help determine if a QPRT is right for your client.
-
Sample QPRT Administration Memo to Client
Trusts & Estates, Advanced Tax Planning, Qualified Personal Residence Trusts
This is a sample memorandum addressed to the client which outlines the administration of the qualified personal residence trust established by the client. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Exploring How Qualified Personal Residence Trusts (QPRTs) Work
Trusts & Estates, Advanced Tax Planning, Qualified Personal Residence Trusts
Discover the mechanics behind a qualified personal residence trust (QPRT) and gain strategic insights into how the QPRT operates. For an in-depth discussion of QPRTs, see Drafting California Irrevocable Trusts chapter 17.
-
File Closing Checklist (CRTs)
Trusts & Estates, Advanced Tax Planning, Charitable Remainder Trusts
You may use this checklist when closing a client’s file after completing work on their charitable remainder trust (CRT). This checklist assumes that you have handled the execution and funding of the trust but are not involved with its administration until the CRT term expires.
-
Transfer a Business Interest to a CRT
Trusts & Estates, Advanced Tax Planning, Charitable Remainder Trusts
Use this guide when transferring a business interest to a charitable remainder trust (CRT). We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Deed Transferring Real Property to a CRT
Trusts & Estates, Advanced Tax Planning, Charitable Remainder Trusts
This sample deed can be used when a client transfers real property to a charitable remainder trust (CRT) of which the client, their spouse, or registered domestic partner are the sole non-charitable income beneficiaries. You may modify this as needed to conform to the facts of your particular matter.
-
Sample Letter to County Recorder’s Office Requesting Recordation of Deed Transferring Real Property to CRT
Trusts & Estates, Advanced Tax Planning, Charitable Remainder Trusts
This sample letter may be used to request that the county recorder’s office record a deed transferring real property to the trustee of a charitable remainder trust (CRT) of which the client and their spouse are the sole non-charitable income beneficiaries. Fees should be attached as determined by the specific county’s fee schedule.
-
Sample CRT Administration Memo to Client
Trusts & Estates, Advanced Tax Planning, Charitable Remainder Trusts
This is a sample memorandum addressed to the client which outlines the administration of the charitable remainder trust established by the client. This sample memorandum assumes that the client and/or their spouse are the sole income beneficiaries of the trust.
-
Checklist: Before You Start Drafting a CRT
Trusts & Estates, Advanced Tax Planning, Charitable Remainder Trusts
Use this checklist before you start drafting a charitable remainder trust (CRT) to ensure that you have the necessary information about your client and their wishes. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Certificate of Trust (CRT)
Trusts & Estates, Advanced Tax Planning, Charitable Remainder Trusts
This sample certificate of trust may be used to verify the existence of a charitable remainder trust (CRT) and provide key details about its terms, without disclosing the full trust agreement. This certificate of trust allows your clients to present to their banks and financial institutions the critical information about their trust in a manner that complies with Probate Code section 18100.5.
-
Sample Transmittal Letter to Client with Draft CRT
Trusts & Estates, Advanced Tax Planning, Charitable Remainder Trusts
This sample letter may be used to accompany the draft of a jointly settled charitable remainder trust sent to your married clients for review. It offers a brief overview of the trust, outlining key elements such as its structure, dispositive provisions, and the clients’ powers and responsibilities, to ensure that the trust aligns with their estate planning goals.
-
Information and Items to Include in Appraisal Report
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
Use this checklist to ensure that all necessary information is included in an appraisal report. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Crummey Notice and Confirmation of Receipt
Trusts & Estates, Advanced Tax Planning, Irrevocable Life Insurance Trusts
This sample Crummey Notice can be used to provide notice to beneficiaries of their withdrawal rights in connection with gifts made to an irrevocable life insurance trust. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Transmittal Letter to Client with Draft ILIT
Trusts & Estates, Advanced Tax Planning, Irrevocable Life Insurance Trusts
This sample transmittal letter may be used to accompany the draft of an irrevocable life insurance trust sent to the client for review. It offers a brief overview of the trust, highlighting key elements such as its purpose, dispositive provisions, and the client’s responsibilities, to ensure that the trust aligns with the client’s estate planning goals.
-
Calculate the ILIT Gift Value
Trusts & Estates, Advanced Tax Planning, Irrevocable Life Insurance Trusts
An irrevocable life insurance trust (ILIT) is a popular estate planning tool used to remove life insurance from the taxable estate of the grantor. Contributing cash or an existing life insurance policy to an ILIT is a common practice in estate planning.
-
Sample Deed of Gift Transferring Funds to an ILIT
Trusts & Estates, Advanced Tax Planning, Irrevocable Life Insurance Trusts
This sample Deed of Gift may be used when the client makes an inter vivos gift of cash to an irrevocable life insurance trust (ILIT) settled by the client. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Closing Letter to Client re: Completion of ILIT
Trusts & Estates, Advanced Tax Planning, Irrevocable Life Insurance Trusts
This sample letter may be used to commemorate the completion of work relating to the establishment and initial funding of a client’s irrevocable life insurance trust, and to terminate the representation of such client until further work is needed. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Certificate of Trust (ILIT)
Trusts & Estates, Advanced Tax Planning, Irrevocable Life Insurance Trusts
This sample certificate of trust may be used to verify the existence of an irrevocable life insurance trust (ILIT) and provide key details about its terms, without disclosing the full trust agreement. A trustee can present a certification of trust to third parties to confirm their authority and powers under trust while keeping the trust's terms confidential.
-
Sample Advice and Warning Letter to Client Regarding Irrevocable Life Insurance Trust
Trusts & Estates, Advanced Tax Planning, Irrevocable Life Insurance Trusts
This sample letter may be used when counseling a client about the benefits, drawbacks, and potential risks associated with implementing an irrevocable life insurance trust. By understanding how this trust works and its implications, the client can make a more informed decision about whether it aligns with their long-term financial and estate planning objectives.
-
Before You Start Drafting an ILIT
Trusts & Estates, Advanced Tax Planning, Irrevocable Life Insurance Trusts
Use this checklist before you start drafting an irrevocable life insurance trust (ILIT) to ensure that you have the necessary information about your clients and their wishes. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Preparing for the Signing Appointment (ILITs)
Trusts & Estates, Advanced Tax Planning, Irrevocable Life Insurance Trusts
Refer to this checklist to confirm you have all the necessary documents and information for the signing appointment with your client establishing an irrevocable life insurance trust (ILIT). We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Fund the ILIT
Trusts & Estates, Advanced Tax Planning, Irrevocable Life Insurance Trusts
An irrevocable life insurance trust (ILIT) is a popular estate planning tool used to remove life insurance from the taxable estate of the grantor. To maximize the benefits of an ILIT, it needs to be properly funded.
-
Is an ILIT Right for Your Client?
Trusts & Estates, Advanced Tax Planning, Irrevocable Life Insurance Trusts
When considering an irrevocable life insurance trust (ILIT) for a client’s estate planning strategy, it is important to evaluate the client’s unique financial and personal circumstances to determine if it is an appropriate estate planning tool. Use this guide to help determine if an ILIT is right for your client.
-
Structuring an Irrevocable Life Insurance Trust
Trusts & Estates, Advanced Tax Planning, Irrevocable Life Insurance Trusts
Gain strategic insight on structuring an irrevocable life insurance trust (ILIT) to achieve tax savings. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Exploring How Irrevocable Life Insurance Trusts Work
Trusts & Estates, Advanced Tax Planning, Irrevocable Life Insurance Trusts
Discover the mechanics behind an Irrevocable Life Insurance Trust (ILIT) and gain strategic insights into how the ILIT operates both during and after the grantor’s lifetime. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample IDGT Administration Memorandum to Client
Trusts & Estates, Advanced Tax Planning, Intentionally Defective Grantor Trusts
This is a sample memorandum addressed to the client that outlines the administration of the intentionally defective grantor trust established by the client for the benefit of their children and descendants. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Transmittal Letter to Client with Draft IDGT
Trusts & Estates, Advanced Tax Planning, Intentionally Defective Grantor Trusts
This sample letter may be used to accompany the draft of an intentionally defective grantor trust sent to the client for review. It offers a brief overview of the trust, highlighting key elements such as its purpose, dispositive provisions, and the client’s responsibilities, to ensure that the trust aligns with the client’s estate planning goals.
-
Sample Letter to County Recorder’s Office Requesting Recordation of Deed Transferring Real Property to IDGT
Trusts & Estates, Advanced Tax Planning, Intentionally Defective Grantor Trusts
This sample letter may be used to request that the county recorder’s office record a deed transferring real property to the trustee of an intentionally defective grantor trust (IDGT). Fees should be attached as determined by the specific county’s fee schedule.
-
Sample Fixed Interest Installment Note (IDGTs)
Trusts & Estates, Advanced Tax Planning, Intentionally Defective Grantor Trusts
This sample fixed interest promissory note may be used when selling an asset to the trustee of an intentionally defective grantor trust. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Demand Promissory Note (IDGTs)
Trusts & Estates, Advanced Tax Planning, Intentionally Defective Grantor Trusts
This sample demand promissory note (which includes interest rate adjustments for the demand feature) may be used when selling an asset to the trustee of an intentionally defective grantor trust. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Closing Letter to Client re: Completion of IDGT
Trusts & Estates, Advanced Tax Planning, Intentionally Defective Grantor Trusts
This sample letter may be used to commemorate the completion of work relating to the establishment and initial funding of a client’s intentionally defective grantor trust, and to terminate the representation of such client until further work is needed. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Transfer a Business Interest to an IDGT
Trusts & Estates, Advanced Tax Planning, Intentionally Defective Grantor Trusts
Use this guide when transferring a business interest to an Intentionally Defective Grantor Trust (IDGT). We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Deed of Gift (Evidencing Transfer of Business Interest to an IDGT)
Trusts & Estates, Advanced Tax Planning, Intentionally Defective Grantor Trusts
This sample Deed of Gift may be used when the client makes an inter vivos gift of an interest in their business to an Intentionally Defective Grantor Trust settled by the client. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Letter to Financial Institution Requesting Transfer of Assets to IDGT
Trusts & Estates, Advanced Tax Planning, Intentionally Defective Grantor Trusts
This sample letter may be used to request the transfer of a client’s individual financial assets into an account at the same financial institution in the name of the trustee of an intentionally defective grantor trust (IDGT) settled by the client. This sample assumes that the trustee of the IDGT has already opened a new trust account in the name of the trustee of the IDGT.
-
Transfer Real Property and Financial Accounts to an IDGT
Trusts & Estates, Advanced Tax Planning, Intentionally Defective Grantor Trusts
Use this guide when transferring real property and financial accounts to an Intentionally Defective Grantor Trust (IDGT). We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Advice and Warning Letter to Client Regarding Intentionally Defective Grantor Trust
Trusts & Estates, Advanced Tax Planning, Intentionally Defective Grantor Trusts
This sample letter may be used when counseling clients about the benefits, drawbacks, and potential risks associated with implementing an intentionally defective grantor trust. By understanding how this trust works and its implications, the client can make a more informed decision about whether it aligns with their long-term financial and estate planning objectives.
-
Preparing for the Signing Appointment (IDGTs)
Trusts & Estates, Advanced Tax Planning, Intentionally Defective Grantor Trusts
Refer to this checklist to confirm you have all the necessary documents and information for the signing appointment with your married couple clients establishing an Intentionally Defective Grantor Trust (IDGT). We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Certificate of Trust (IDGT)
Trusts & Estates, Advanced Tax Planning, Intentionally Defective Grantor Trusts
This sample certificate of trust may be used to verify the existence of an intentionally defective grantor trust (IDGT) and provide key details about its terms, without disclosing the full trust agreement. A trustee can present a certification of trust to third parties to confirm their authority and powers under trust while keeping the trust's terms confidential.
-
Before You Start Drafting an IDGT
Trusts & Estates, Advanced Tax Planning, Intentionally Defective Grantor Trusts
Use this checklist before you start drafting an intentionally defective grantor trust (IDGT) to ensure that you have the necessary information about your client and their wishes. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Structuring an Intentionally Defective Grantor Trust
Trusts & Estates, Advanced Tax Planning, Intentionally Defective Grantor Trusts
Gain strategic insight on structuring an irrevocable dynasty trust as an intentionally defective grantor trust (IDGT) to achieve tax savings. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Exploring How Intentionally Defective Grantor Trusts (IDGTs) Work
Trusts & Estates, Advanced Tax Planning, Intentionally Defective Grantor Trusts
Discover the mechanics behind an intentionally defective grantor trust (IDGT) and gain strategic insights into how the IDGT operates both during and after the grantor’s lifetime. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Trust Funding Memorandum
Trusts & Estates, Estate Planning, Estate Planning for Married Couples, Qualified Domestic Trusts, Advanced Tax Planning, Marital Deduction Trusts
Use this sample funding memorandum to instruct your married clients on how to formally transfer their assets into their revocable trust. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Agenda for Strategic Planning Meeting with Adviser Team
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
Use this Checklist during the initial strategic planning meeting with the client’s other advisers to share information, leverage combined expertise, and work collaboratively to create a succession planning strategy that will meet the client’s business succession planning goals. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Letter Confirming Outcome of Pre-Implementation Adviser Team Meeting
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
This sample letter to the members of the client’s multidisciplinary adviser team may be used to confirm the outcome of a meeting to finalize the implementation of the client’s business succession plan. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Closing Letter to Client – Completion of Business Succession Plan
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
This is a sample letter that may be used to commemorate the completion of a client’s business succession plan and terminate the representation of such client until further work is needed. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Fixed Interest Installment Note (Business Succession Planning)
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
This sample fixed interest installment note may be used in business succession planning. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Sample Demand Promissory Note (Business Succession Planning)
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
This sample demand promissory note (which includes interest rate adjustments for the demand feature), may be used in business succession planning. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Transfer a Business Interest to a Trust
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
Use this guide when transferring a business interest to seamlessly integrate the client’s business succession plan with their estate plan. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Coordinate with the Client’s Multidisciplinary Adviser Team
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
Use this guide in a business succession planning matter to help assemble and coordinate a client’s multidisciplinary adviser team, which is essential for developing an effective plan that aligns with the client’s business and estate planning goals. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Clause Regarding Termination Within Specified Period After Death of Senior Family Member
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
This sample clause may be used in business succession planning when requiring termination or dissolution of a limited liability corporation (LLC) after a certain amount of time has passed following the death of the business owner. This clause is for use in an LLC operating agreement.
-
Integrate the Client’s Business Succession Plan With Their Estate Plan Using Revocable and Irrevocable Trusts
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
Integrating a client’s succession plan with their estate plan is essential to ensure a smooth transition of the business to the succeeding generation while minimizing tax burdens and potential conflicts. Use this guide to assist with integrating a client’s business succession plan with their estate plan using revocable living trusts and irrevocable trusts.
-
Transfer Assets to a Business Entity
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
Use this guide for instructions on how to transfer various types of assets that are commonly transferred to a business entity. We completed legal editing and analysis of authorities cited here as of the date listed above.
-
Sample Business Succession Planning Memorandum to Client
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
This sample business succession planning memorandum discusses the key elements of a hypothetical business succession plan for married clients involving a part sale-part gift of the common interests in the client’s limited liability company to an intentionally defective grantor trust (IDGT), life insurance, and modification of the clients’ existing estate planning documents in order to integrate them with the business succession plan. We completed legal editing and analysis of authorities cited here as of the date listed below.
-
Confirm a Business Succession Plan with the Client, Obtain Authorization to Proceed, and Manage Workflow
Trusts & Estates, Estate Planning, Business Succession Planning For Closely Held & Family Businesses
Use this guide to address the basic steps for confirming a business succession plan with the client, obtaining their authorization to proceed, and managing workflow once implementation of the plan begins. This analysis requires that you have already gathered basic information from your clients regarding their goals, concerns, assets, and family situation, and that you have used this information to develop a preliminary business succession plan.
No programs found.
No secondary sources available.
Scroll to TopCopy the link below: